Colombia is three markets, and you have to pick one
The city with the demand is not the city with the port, and the workforce behaves differently in each. Everything written about this in English is about where to live.
Read the article →The route into northern South America, three distinct commercial hubs
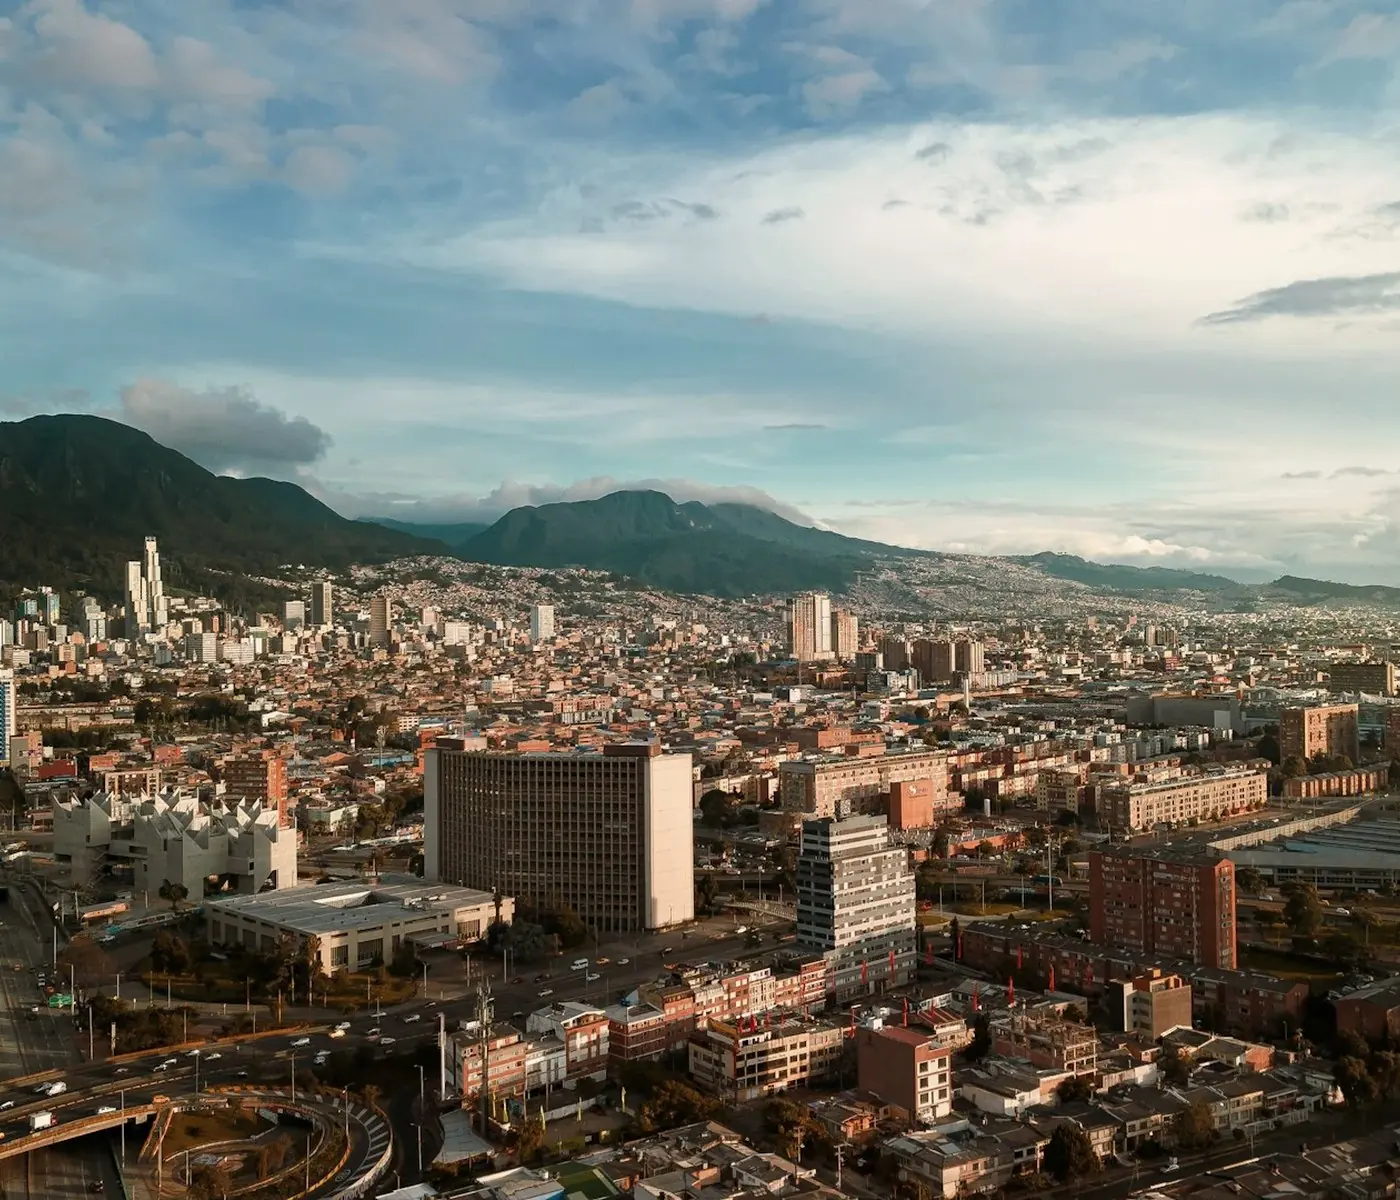
The route into the northern half of South America. Pacific Alliance membership, significant infrastructure spending and a services sector that has absorbed foreign entrants well. Bogotá, Medellín and Barranquilla behave as three distinct commercial markets.
Colombia is the domestic-demand market of the four. Trade runs at 35 per cent of GDP, less than half Mexico's 80 per cent, so the commercial logic is selling to 53 million Colombians rather than using the country as an export platform. An entrant arriving with a re-export thesis usually has the wrong country.
Foreign direct investment reached 11.6 billion dollars in 2025 on 2.6 per cent growth. The practical complication is internal: Bogotá, Medellín and Barranquilla behave as three commercial markets with different channels, and a distributor who is strong in one is often absent from the others.
Population, GDP, GDP per capita, growth, trade share and foreign direct investment: World Bank, 2025, in current US dollars. The US trade share is 2024 and Guatemalan FDI is 2024, the latest available in each case. Chile's copper output is USGS Mineral Commodity Summaries 2026.
Country and sector reports, competitive benchmarking, mapping of the players who actually control the channel.
Local standards, certification routes, import and export procedure, legal structure and tax overview.
Distributors, agents, clients and suppliers, with background checks and arranged B2B meetings.
Entry route, distribution model, pricing and competitive positioning, argued against the alternatives.
Checked September 2026. Every figure below is linked to the institution that published it, with the period it refers to.
Labour informality ran at 33.3 per cent in Bogotá, 38.1 per cent in Medellín and 49.5 per cent in Barranquilla in the quarter to June 2026, against 54.5 per cent nationally. That spread of sixteen points between Bogotá and Barranquilla is the single clearest number behind our view that Colombia is three commercial markets rather than one. Where half the workforce is informal, formal-channel distribution reaches a smaller share of actual consumption, invoicing behaviour differs, and the documented credit history you would normally use to qualify a distributor largely does not exist.
Colombia's simple average applied MFN tariff on non-agricultural goods was 5.3 per cent in 2024, with 61.2 per cent of non-agricultural lines already duty free. Agriculture averages 16.1 per cent. Most EU industrial goods enter free under the EU and Colombia trade agreement. The tariff is not where Colombian landed cost is decided, which is why we do not spend client time on tariff engineering here.
Ley 2024 de 2020 caps business-to-business payment terms at 45 calendar days from receipt of the goods or completion of the service, and clauses that breach it are void. The exception matters more than the rule: the cap does not apply where both parties are large enterprises. A European manufacturer selling to a large Colombian retailer or industrial group therefore has no statutory protection on payment terms and negotiates them as it would anywhere. The same manufacturer selling to small and medium distributors has a legal floor it can hold. Establish which side of that line each customer sits on before you set terms, not after.
The Cartagena port zone handled 69.7 per cent of Colombia's containerised tonnage in the first half of 2026, and around 65 per cent of TEUs. Buenaventura on the Pacific and Santa Marta and Barranquilla on the Caribbean carry the rest. Concentration on one zone is convenient until it is not: one point of entry is one point of failure for labour action, weather and congestion, and the inland haul from Cartagena to Bogotá is long. A Colombian landed cost modelled on ocean freight alone leaves out the part that varies most.
The city with the demand is not the city with the port, and the workforce behaves differently in each. Everything written about this in English is about where to live.
Read the article →The warning label and the health tax are the same decision, and no English-language source treats them as one. For a European confectionery or charcuterie exporter they arrive together.
Read the article →The promotional pages still lead with 20 per cent instead of the 35 per cent general rate. They do not lead with the condition attached to it since 2022, which most European entrants cannot meet.
Read the article →A 20 per cent withholding on a gross service fee is not a 20 per cent tax. On a project with a 30 per cent margin it takes roughly two thirds of the profit, and no treaty exists to reduce it.
Read the article →Every guide explains how to file. The question that decides your Colombian entry is whose name goes on it, and almost nobody asks it before signing.
Read the article →Most European industrial goods enter Colombia at zero duty and still cost a fifth more than the invoice by the time they clear. The tax is charged on a base that includes the duty you did not pay.
Read the article →The five problems that most often derail a European entry into Latin America, and why each one is worst in a different country.
Read the article →The terms of trade between Europe and Mexico moved twice in 2026. Here is what that changes for a European exporter, and who should still stay away.
Read the article →Both give EU goods duty free access and neither accepts your CE mark. What actually decides it: size, what happens when origin fails, payment law, termination law and treaties.
Read the article →Registering the investment with the central bank is what creates the right to remit. It is an administrative step with a permanent consequence if it is missed.
Read the article →RETIE is a lead time item, not a cost item. European manufacturers keep discovering it after the order is won, which is the worst possible moment.
Read the article →Everyone answering this question sells incorporations, so everyone answers yes. For most European exporters the honest answer is not yet, and here is the line.
Read the article →Colombia has a statutory formula, and a rule that voids your choice of foreign law. Calling the contract distribution rather than agency does not decide which one you are in.
Read the article →A map of the legal and administrative questions a European company must ask before entering Latin America, and where the answers usually differ from home.
Read the article →Entry asks whether to be present at all. Expansion asks how to get more from a position you hold. Running the wrong playbook is expensive.
Read the article →Tell us the sector and the decision you are facing. A thirty-minute scoping call is enough for us to say how we would approach it, and whether we are the right people for it.
